Funded
Toronto restaurant
A Toronto restaurant, funded with TD. We built the plan, the numbers and every document, and saw it through to funding.
For relationship managers
We bring complete Canada Small Business Financing Program (CSBFP) files in the restaurant, retail, medical professional and agriculture sectors, built to the standard your credit team already works to. Your bank makes the loan. We don't lend. No coaching the client, no chasing documents. And we send good clients your way too.
Start with one file.If it arrives the way it should, send us the next one.
Banks and credit unions we work with
What we take off your desk
We do the file work you don't have time for. You keep the client and the deal, and we send good clients your way too.
A business plan, a formula-linked three-year model with every assumption visible, capex reconciled to quotes, and the document package, organized in a data room your credit team can move through quickly. We are not a lender, and we only bring you files you have told us you want.
Tax returns, credit, net worth and equity, lease term against the amortization, and demolition clauses on purchases. Anything that stops a file, we aim to find early.
After approval we prepare the invoices, proof of payment and equity trail for each draw, so the file keeps moving on your side too.
We meet a lot of good, qualified operators who need a banker. When one fits what you lend to, we introduce them. You send some to us, we bring some to you, and we grow together.
What lands on your desk
Every file arrives organized the same way, so your credit team knows where everything is. The folder names match the checklist your client works from.
See the checklist your client works fromData room / your client
How it works with your bank
Send one. Judge us on what comes back.
Their name and a line about the project. We do not reach out to them until you give us the go-ahead.
We look at whether the file can work, and tell the client straight if it cannot. Then we build the plan, the model, the capex and the document package.
Our fees are the client's, and the shared success compensation is only paid on funding. Where your bank allows it, both can sit inside the financed project cost.
Complete and organized for your credit team. We handle the client's side of the back and forth, then support each draw. You get a short note from us at each stage: submitted, approved, first draw.
Brands we've worked with
Funded
Every application we've submitted has been funded. Over $10 million so far, and about 100 hours saved for each client.
Funded
A Toronto restaurant, funded with TD. We built the plan, the numbers and every document, and saw it through to funding.
Funded
An asset purchase rather than a build, which means an appraisal, an inherited lease, and two years of the seller's statements and returns. Financed through a credit union.
Funded
Every document, the plan and the forecast, taken to Meridian and through three rounds of questions to approval.
Funded
A ground-up bar, financed on projections rather than history, because there was no trading history for the location to lean on.
Drag, swipe or scroll sideways.
On Instagram
What comes in each file
Who you deal with
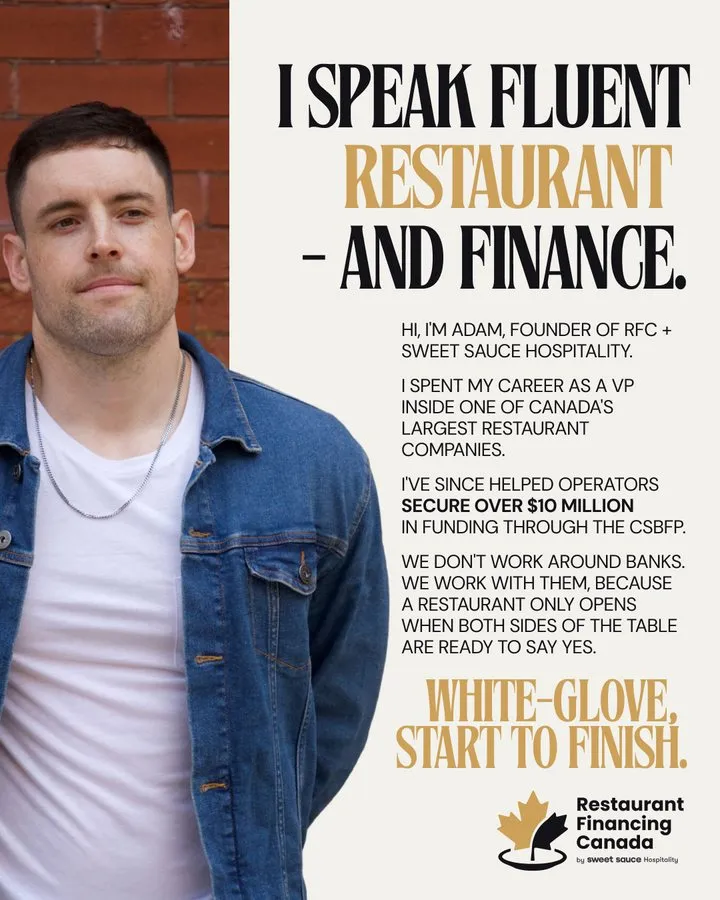
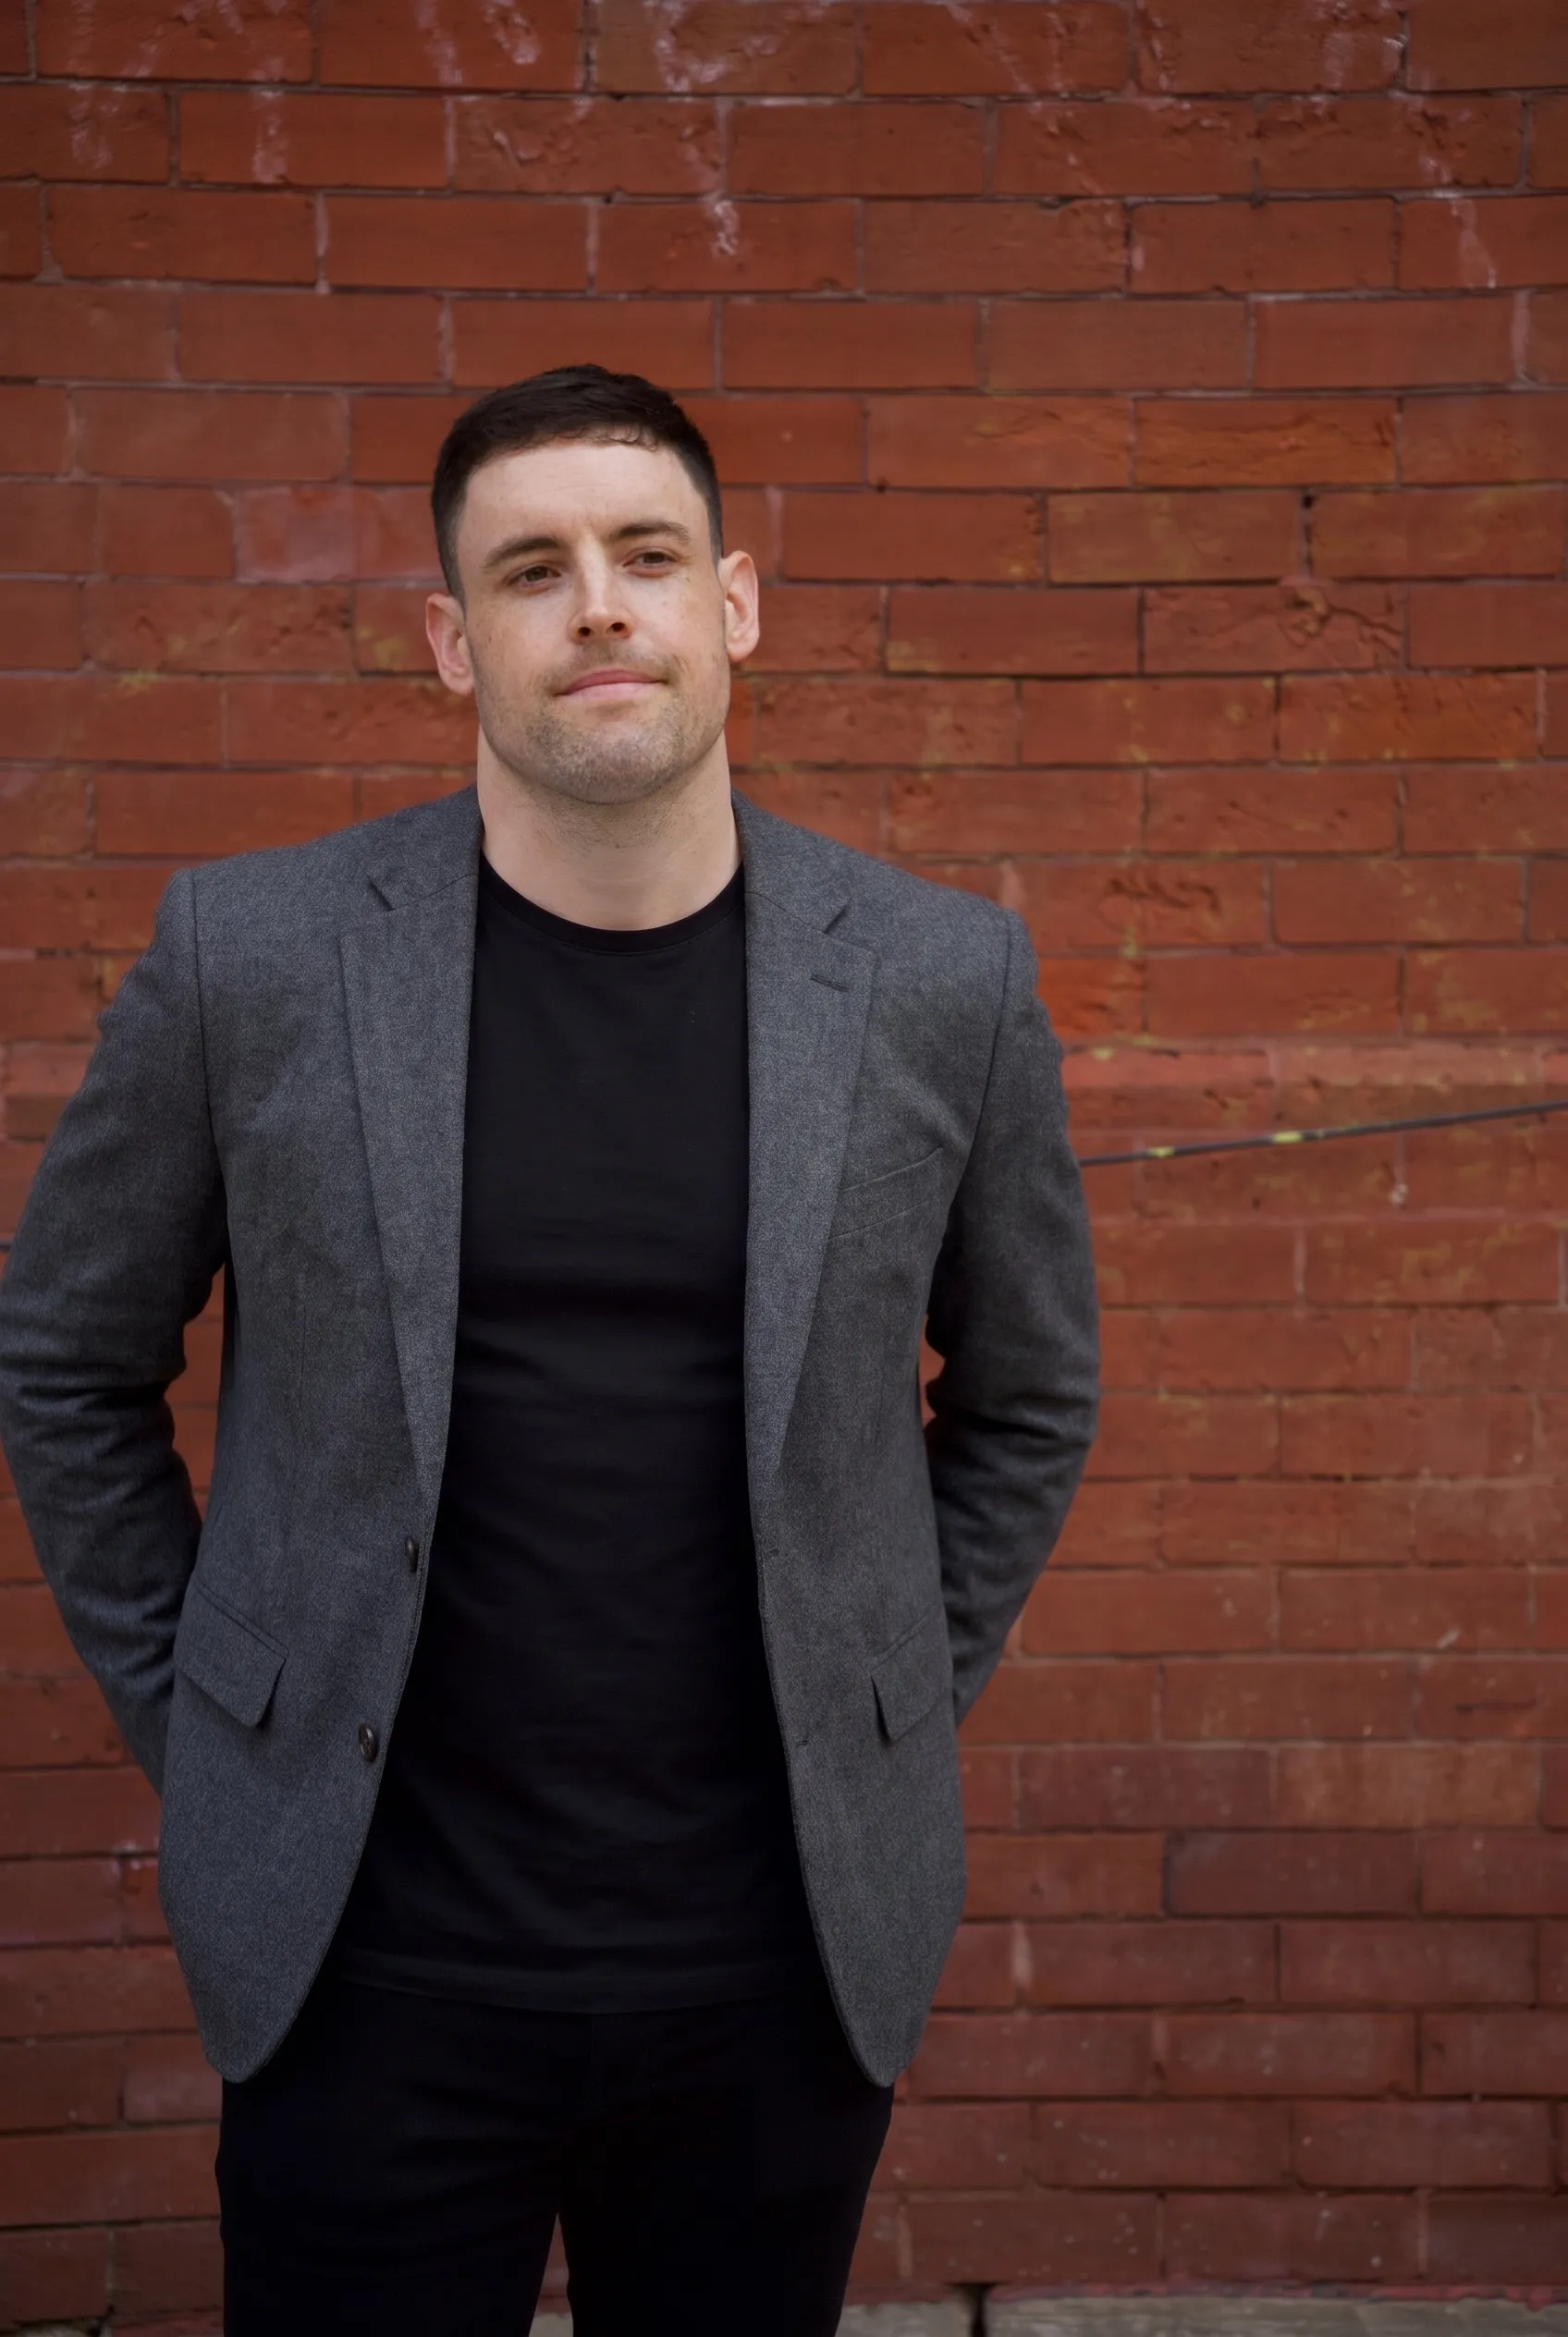
Hi, I'm Adam Gilbert. I've spent my career in the restaurant business, on the finance and marketing side. That includes senior marketing and finance roles at one of Canada's best known restaurant groups, through its sale to the country's largest full-service operator.
I run Sweet Sauce Hospitality Partners, and I am building my own restaurant concepts, so I am not advising from the sidelines. I know what a build really costs, and what the bank will ask before it asks.
A good business plan tells your story, then backs it up with numbers. It has to make the bank believe in your restaurant, and then prove it.
Let's get your clients funded.
Questions
Straight answers to what relationship managers ask first, starting with who we are and who pays us.
Refer a clientMost restaurant owners we work with qualify for between $200,000 and $500,000. The program limit is $500,000 for leasehold improvements, equipment and intangibles such as franchise fees, including up to $150,000 of working capital. If they are buying the building too, the limit is higher.
No. We are a restaurant financing brokerage. We build the file, and the loan comes from the bank or credit union. When you refer a client, the file comes back to you.
The client. There is a project launch investment to start and shared success compensation that is only paid when they are funded. Where the lender allows it, both can be included in the financed project cost.
Most of our files are CSBFP files, and not all of them. Where the project and the security support a conventional facility, we structure the file that way instead.
No. Restaurants are our name and our focus, and we also take on retail, medical professional and agriculture files for CSBFP.
No. When you tell us about someone, we do not reach out until you give us the go-ahead. The introduction is yours to make.
We tell them on the first call rather than taking their time or yours. Some things stop a file through this program, like personal taxes that have not been filed, and some need fixing first, like a lease too short to carry the loan. We would rather find them early than in front of the lender. Where a file can go ahead, the credit decision still belongs to the lender. Nobody can promise approval, and we do not.
Across Canada. The CSBFP is a federal program and we work remotely, so where you are does not matter. We are based in Toronto and work with owners in the Greater Toronto Area, Vancouver, Calgary, Edmonton, Winnipeg, Halifax, Montreal, Ottawa and Quebec City. Montreal, Ottawa and Quebec City are handled in French or English.